Cybersecurity Infographic Series · Banking, Payments and Financial Regulation

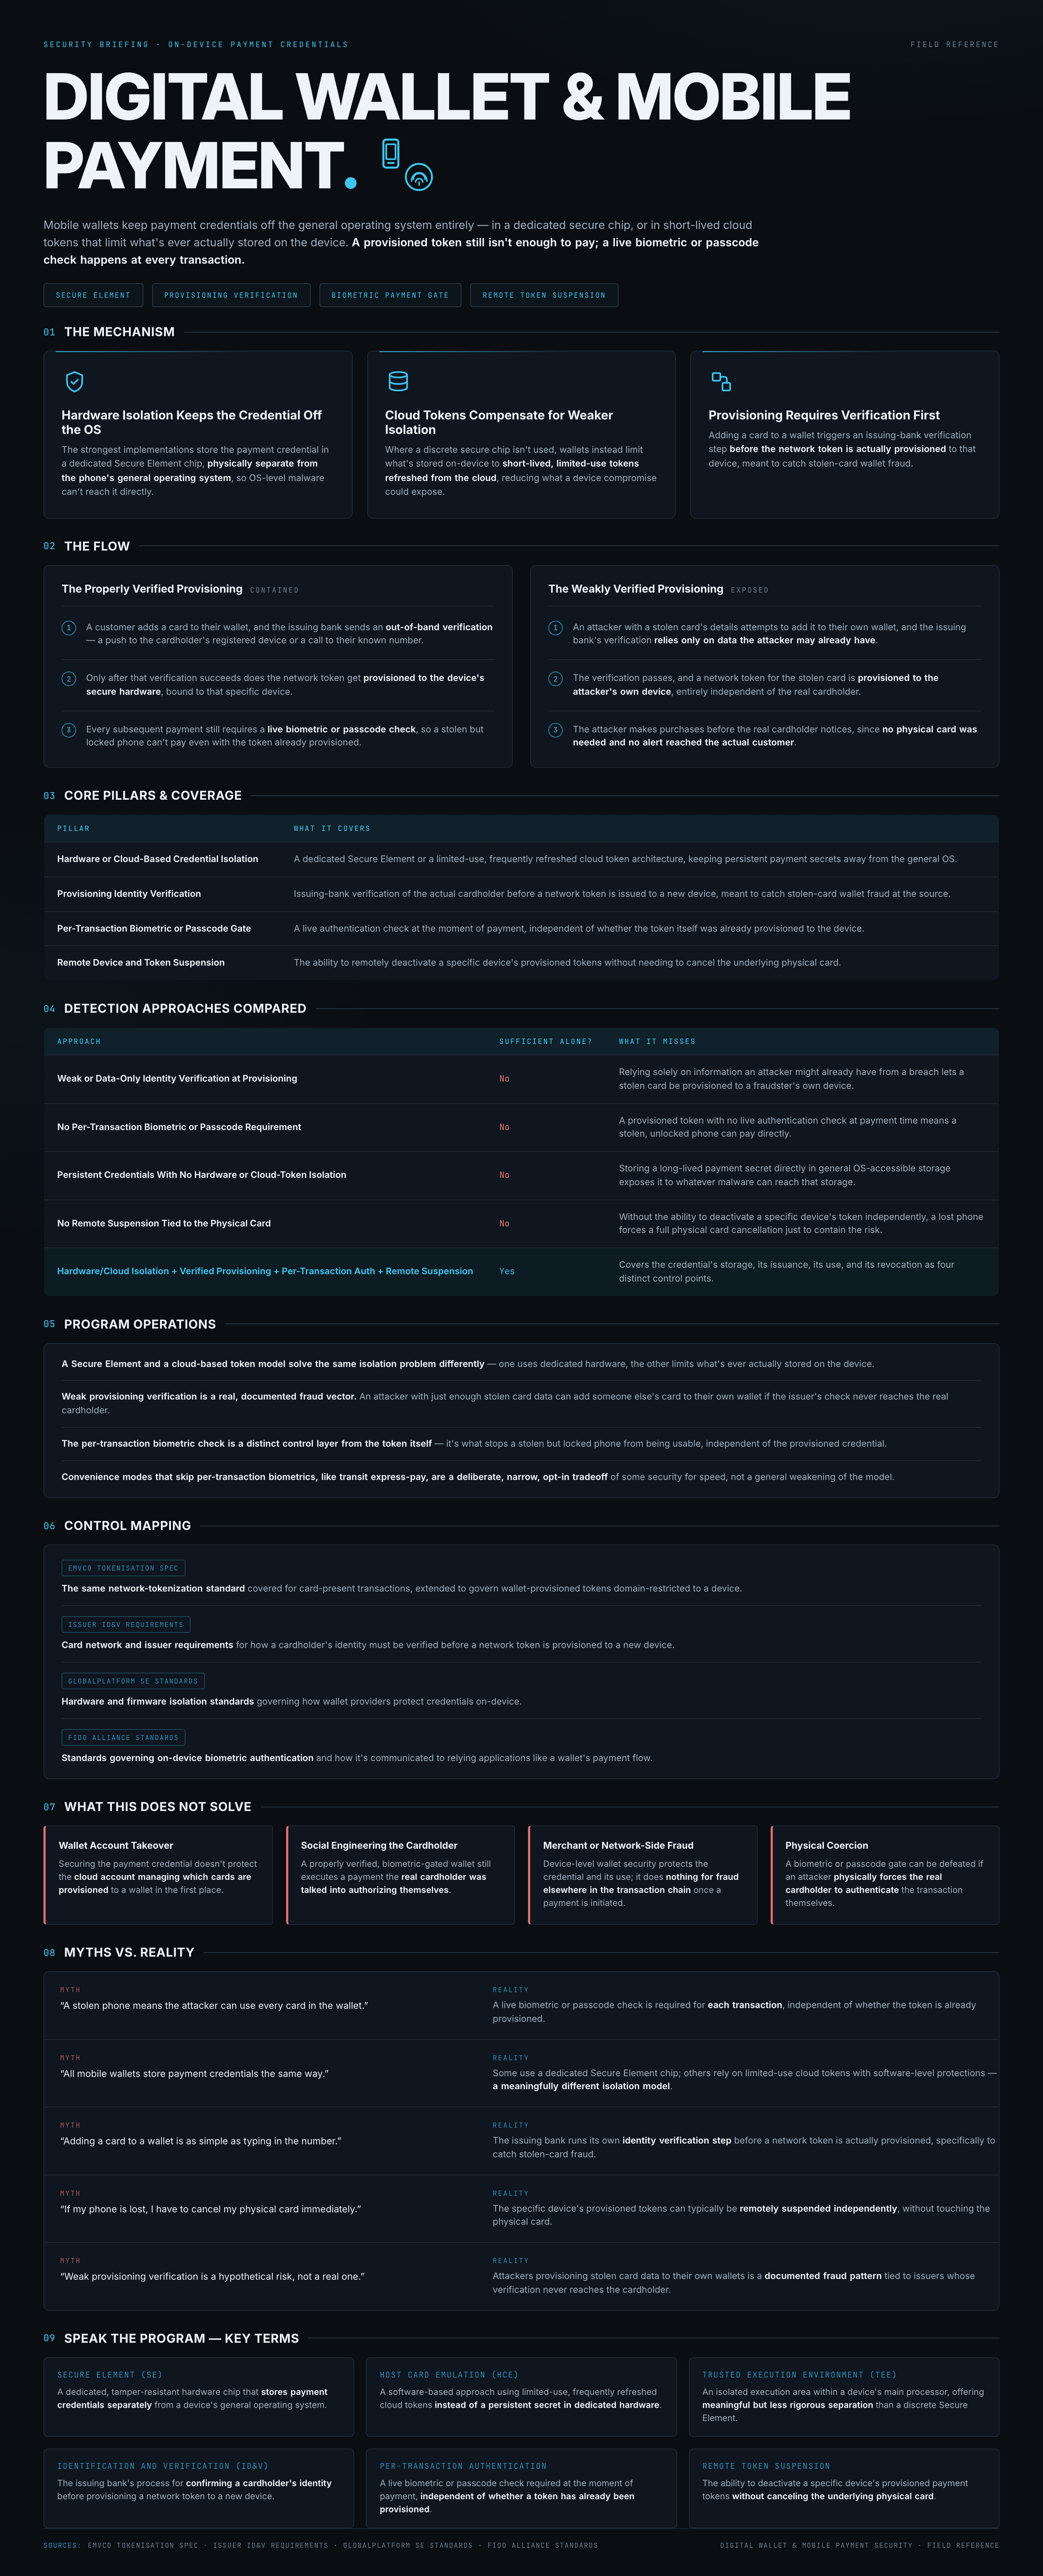
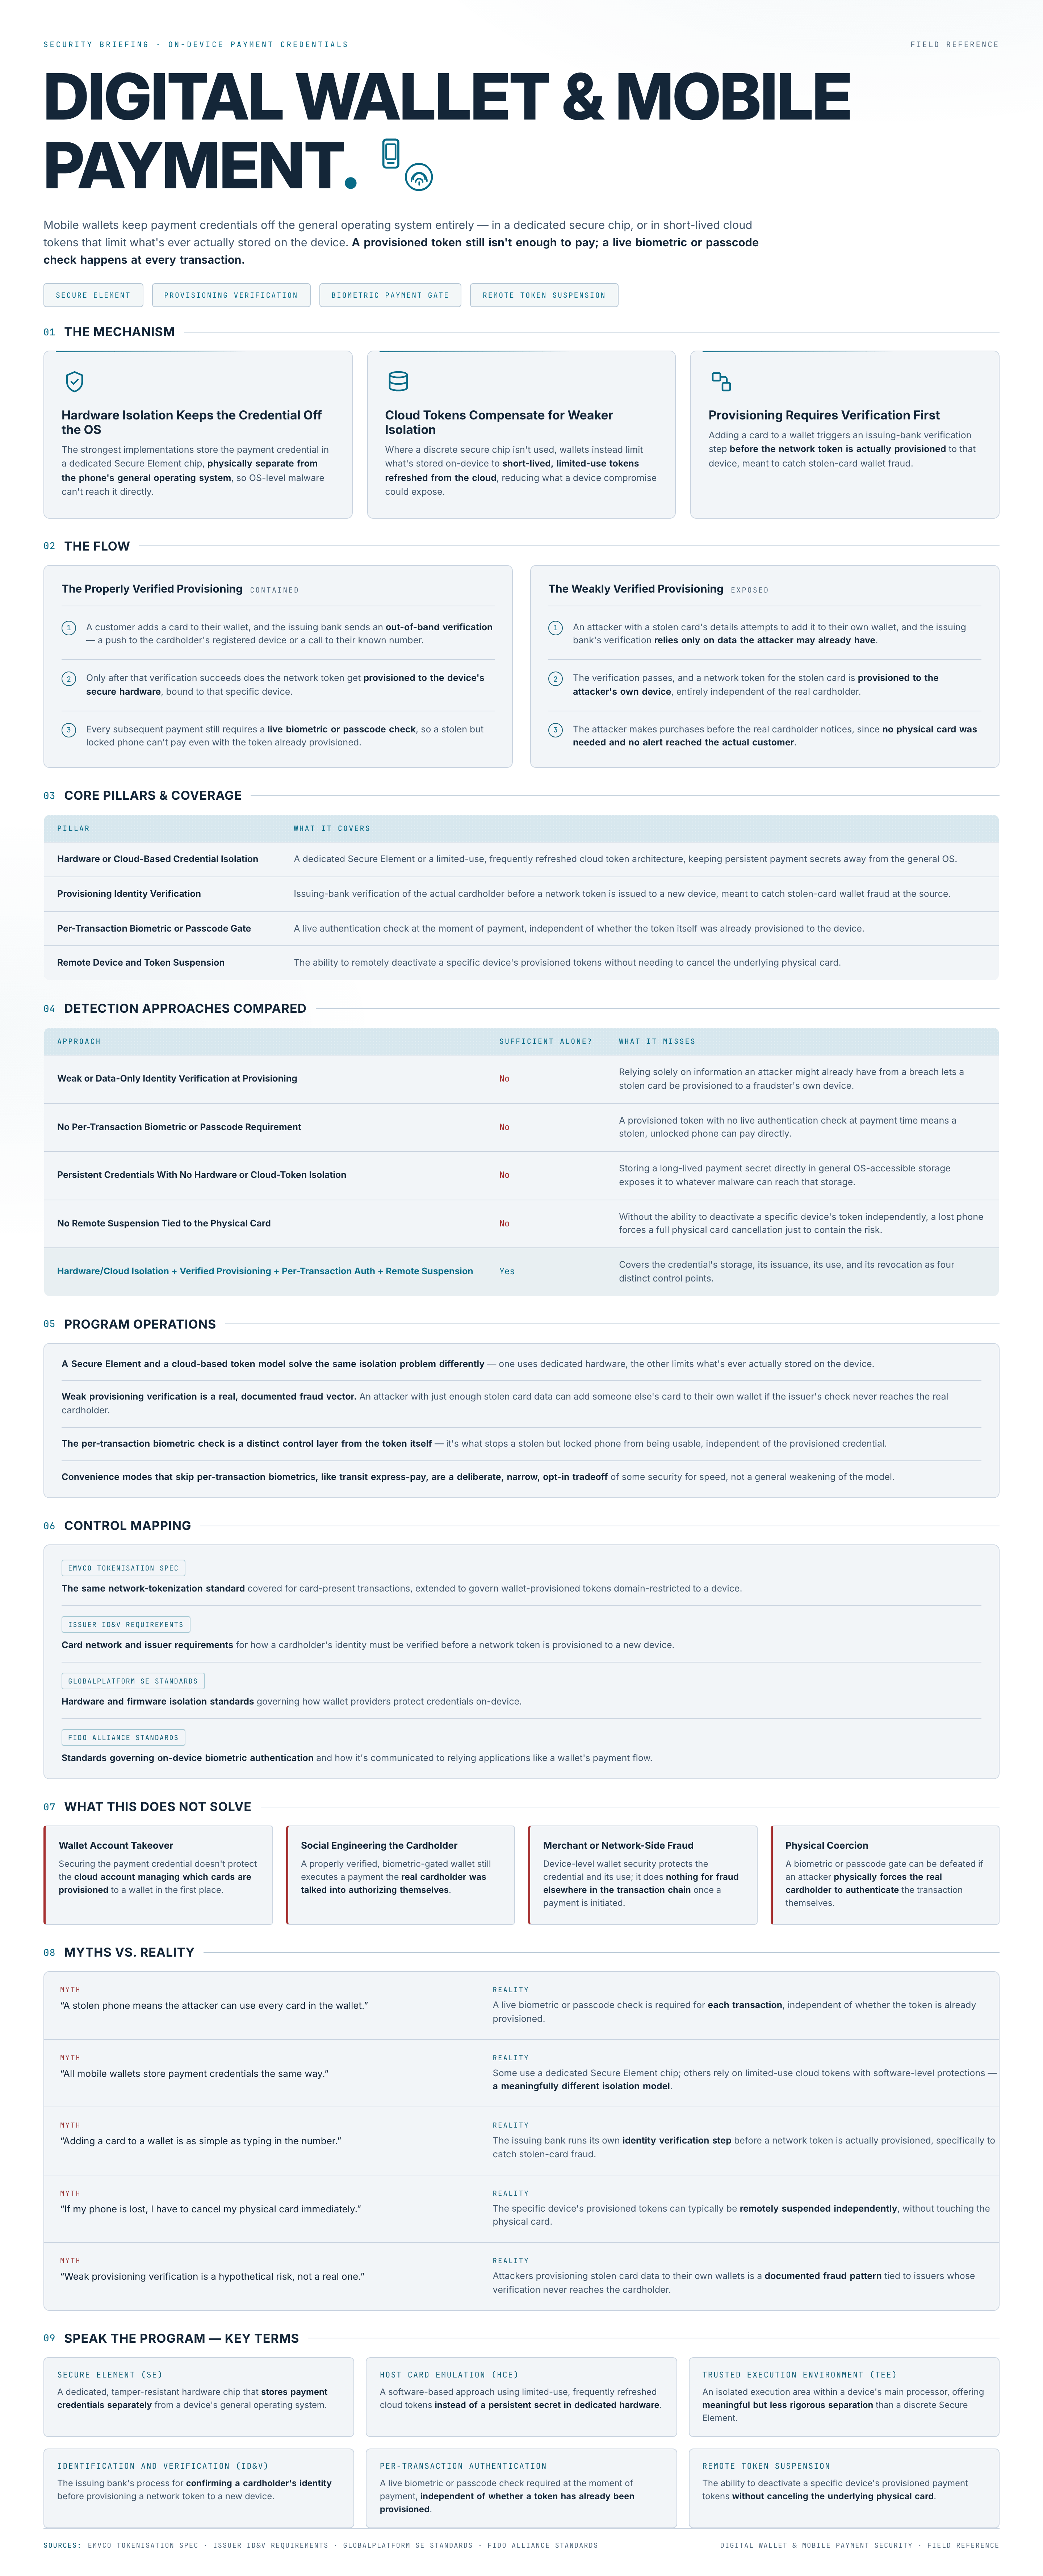
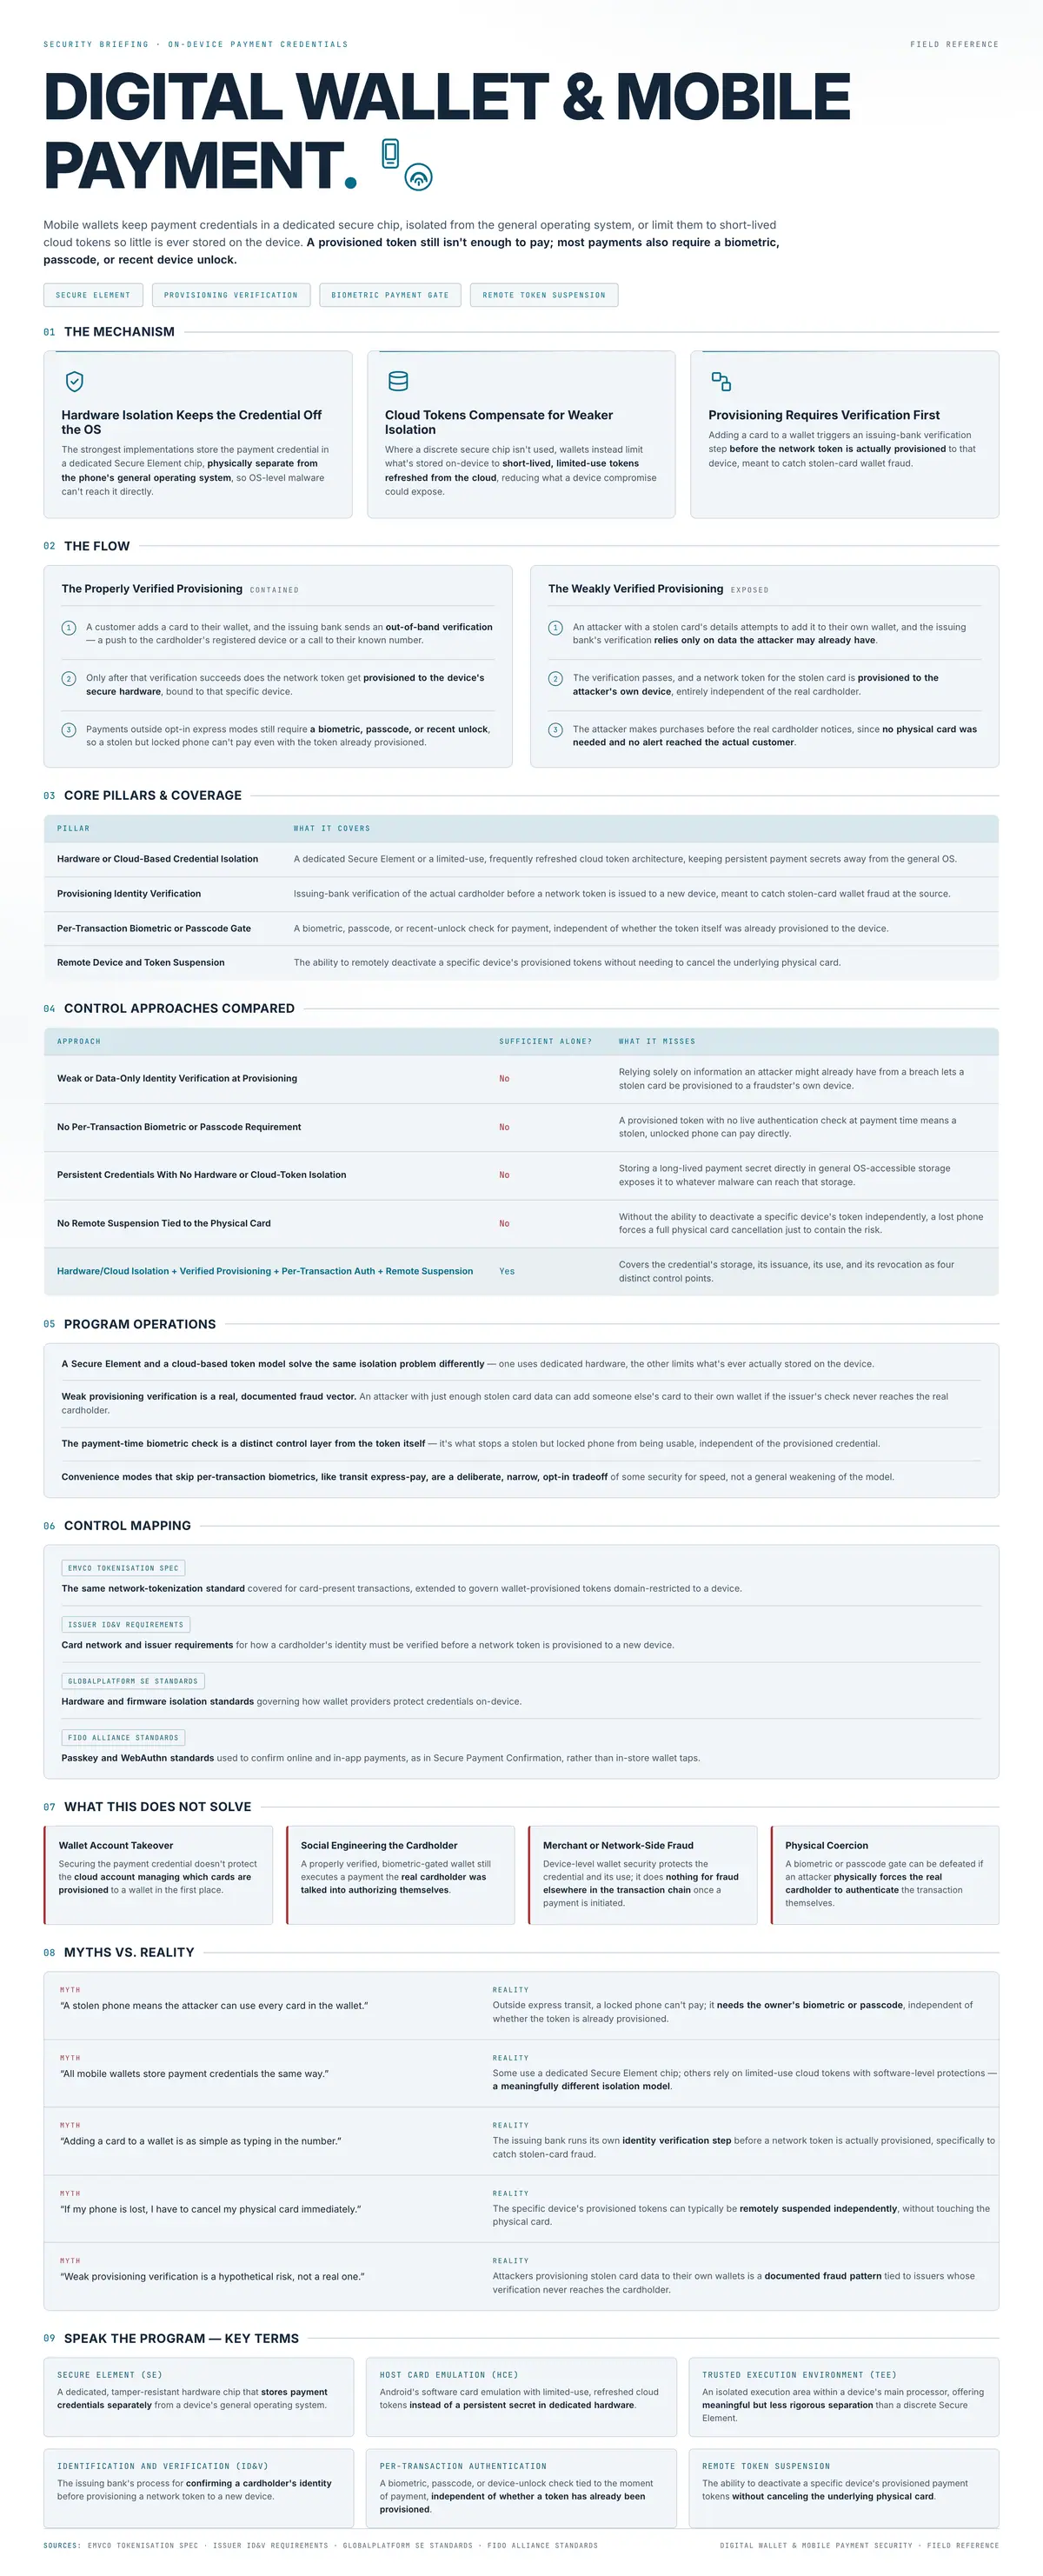
Digital Wallet and Mobile Payment Security

Mobile wallets keep payment credentials in a dedicated secure chip, isolated from the general operating system, or limit them to short-lived cloud tokens so little is ever stored on the device. A provisioned token still isn't enough to pay; most payments also require a biometric, passcode, or recent device unlock.

Downloads

Free to download, no sign-up. Topic 59 of 103 in the series.

More in Banking, Payments and Financial Regulation

Banking, Payments and Financial Regulation

PCI DSS and Payment Card Security

PCI DSS governs any system that stores, processes, or transmits cardholder data — compliance is a continuous state validated at a point in time, not a permanent guarantee, and a poorly scoped assessment can miss most of the real environment.
Banking, Payments and Financial Regulation

SWIFT Customer Security Programme

SWIFT's own network has never been the point of failure in a major payment fraud incident — the customer's local messaging environment consistently is, which is exactly the gap the Customer Security Programme exists to close.

Banking, Payments and Financial Regulation

FFIEC and GLBA Safeguards Rule

GLBA requires every financial institution to safeguard customer data: banks under the Interagency Guidelines that FFIEC-handbook examiners assess, non-banks under the FTC's Safeguards Rule. A policy document that was never operationalized satisfies neither.

Banking, Payments and Financial Regulation

Wire and ACH Transfer Fraud

Almost every successful wire or ACH fraud hinges on one moment: a payment instruction change that looks legitimate enough to act on without independent verification. Once a transfer executes, it's effectively irrevocable — the control has to work before the money moves, not after.

Banking, Payments and Financial Regulation

Real-Time Payments Security

FedNow and the RTP network settle payments in seconds, 24/7/365 — with no ACH-style clearing window or staffed wire review to give fraud interdiction a chance. Once a real-time payment is authorized, prevention has already happened or it hasn't happened at all.

Banking, Payments and Financial Regulation

AML and Transaction Monitoring Security

Transaction monitoring watches ongoing flows for patterns — structuring, layering, unusual velocity — that a single-transaction fraud control was never built to see. But the monitoring system is itself infrastructure, and a rule an insider can quietly disable is a control that was never really there.

Back to the full library